Main & Market Newsletter
A Quarterly Brief for Main Street and Lower Middle Market Dealmakers
Q3 2026
The Quarter
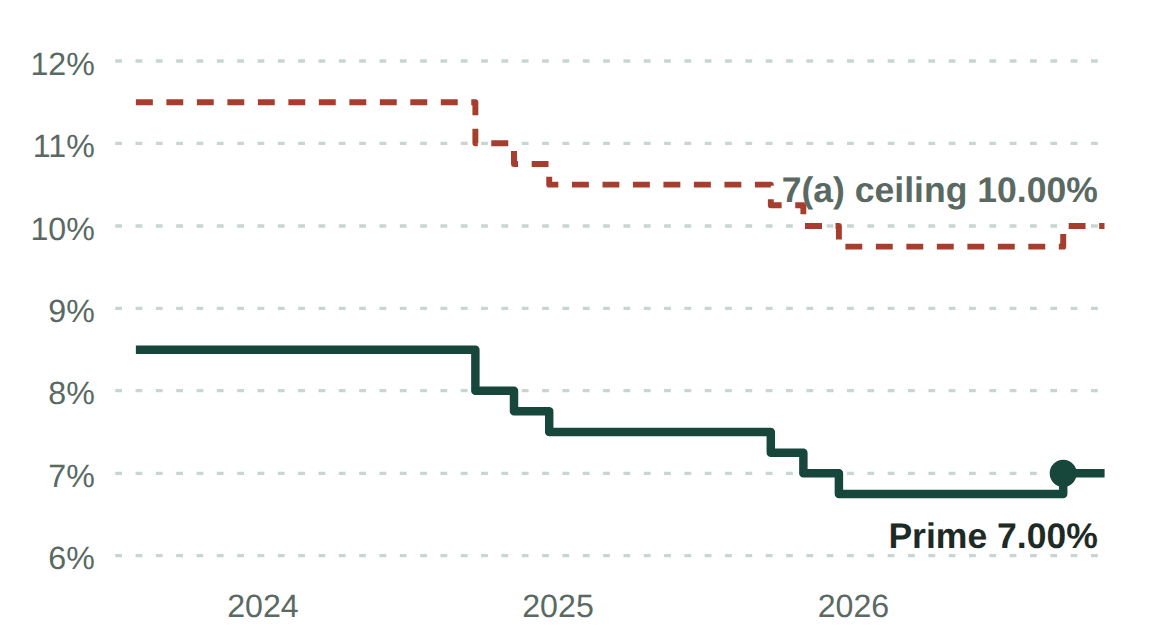
Two dates now frame every SBA-financed acquisition in the pipeline. On September 16 the Federal Reserve raised its target range a quarter point to 3.75%–4.00%, its first increase since 2023, and the prime rate moved to 7.00%. That lifts the ceiling on variable-rate 7(a) acquisition loans above $350,000 to 10.00%. Then on October 1, SOP 50 10 8.1 takes effect: debt-service coverage rises to 1.25x, projections stop counting toward it, and any acquisition priced at $3 million or more needs an independent quality of earnings report. Applications that receive an SBA loan number by September 30 stay under the current rulebook.
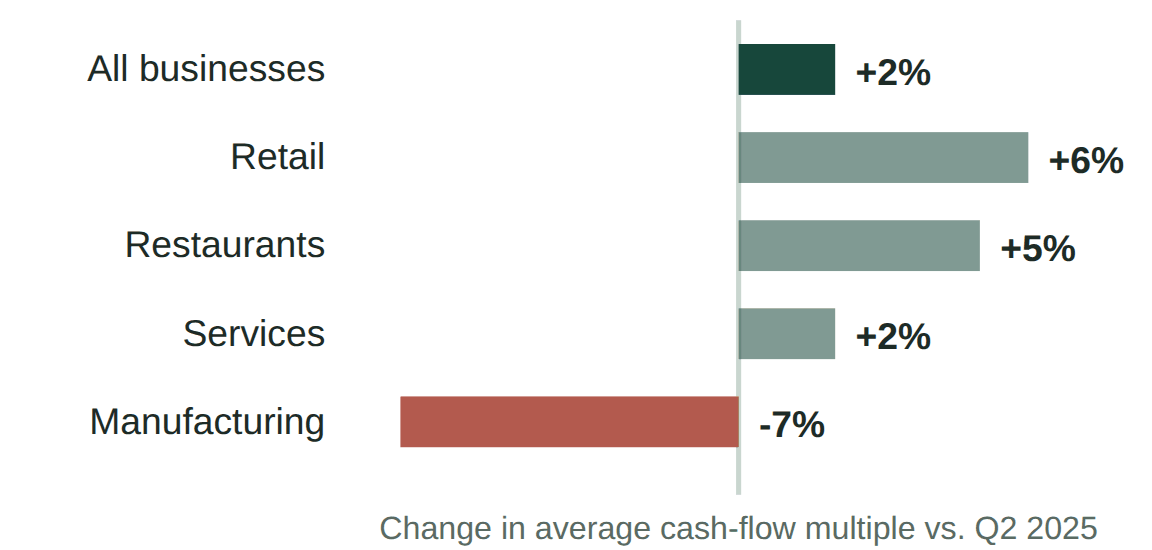
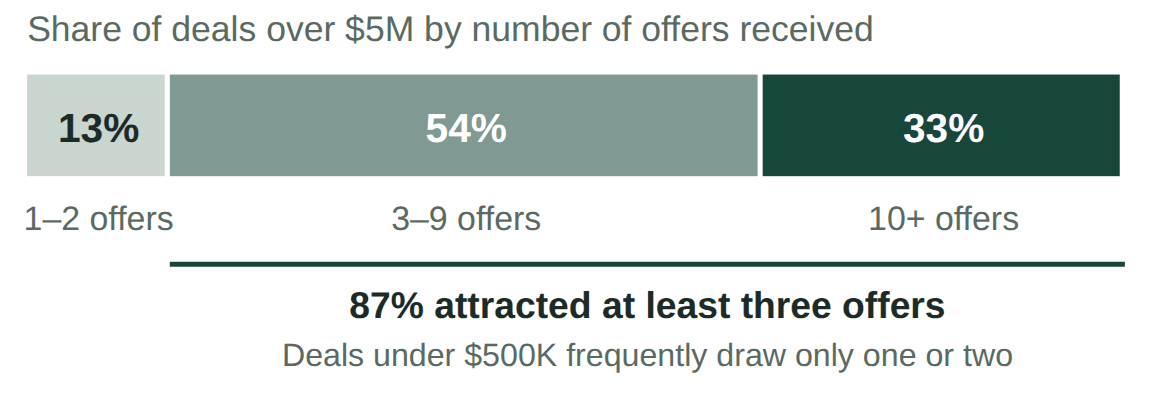
The second-quarter data released over the summer explain why those two dates matter so much. BizBuySell counted 2,117 closed transactions in Q2, down 10% from both the prior quarter and a year earlier, while the average cash-flow multiple held at 2.7x. The IBBA and M&A Source Market Pulse shows the same market from the other end of the size spectrum: 87% of deals over $5 million drew three or more offers, and multiples in the $5M–$50M band reached their highest level since early 2022. Fewer closings, firmer prices, and a widening gap between the businesses lenders will finance and the ones they won't.
By the Numbers
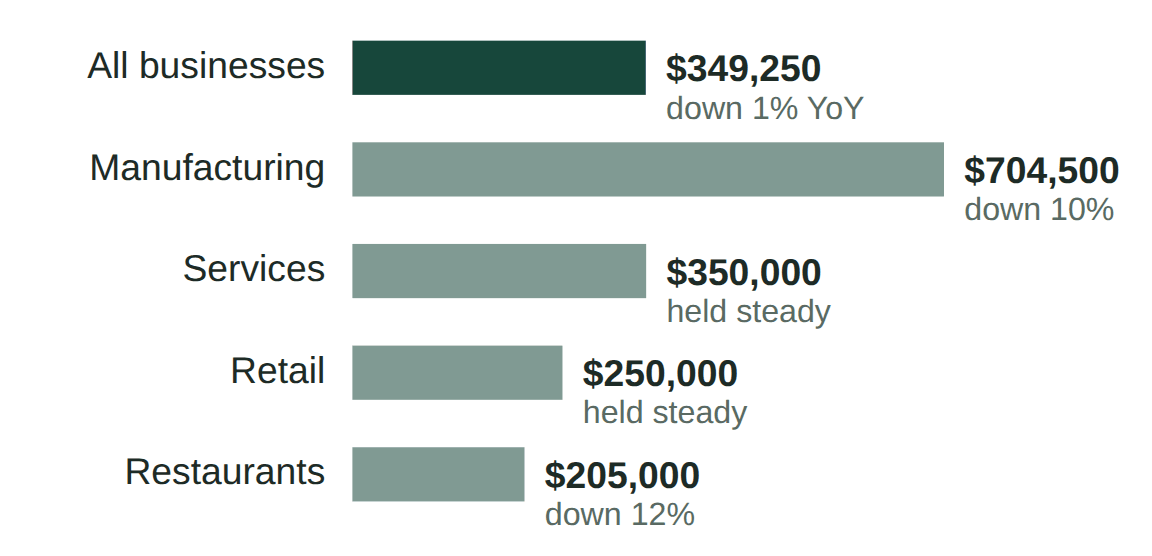
Latest published readings. Quarterly figures are Q2 2026 unless noted. Values marked with an asterisk are derived from the publisher's reported totals and percentage changes rather than stated directly.
Main Street — transactions reported by brokers
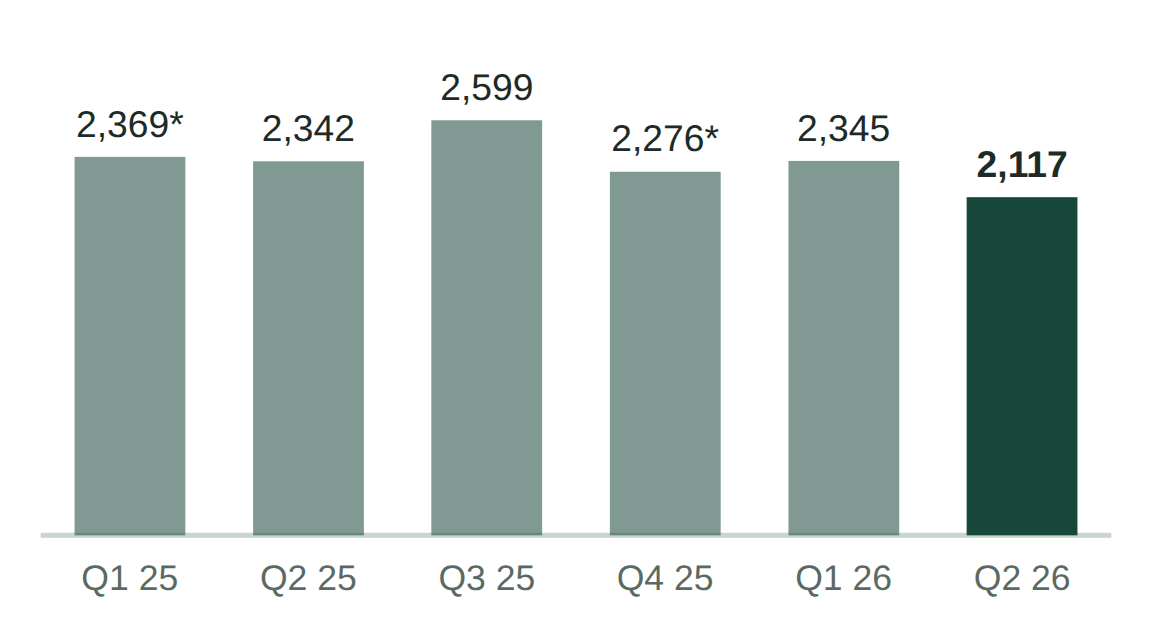
Lower middle market — advisor survey, deals to $50M
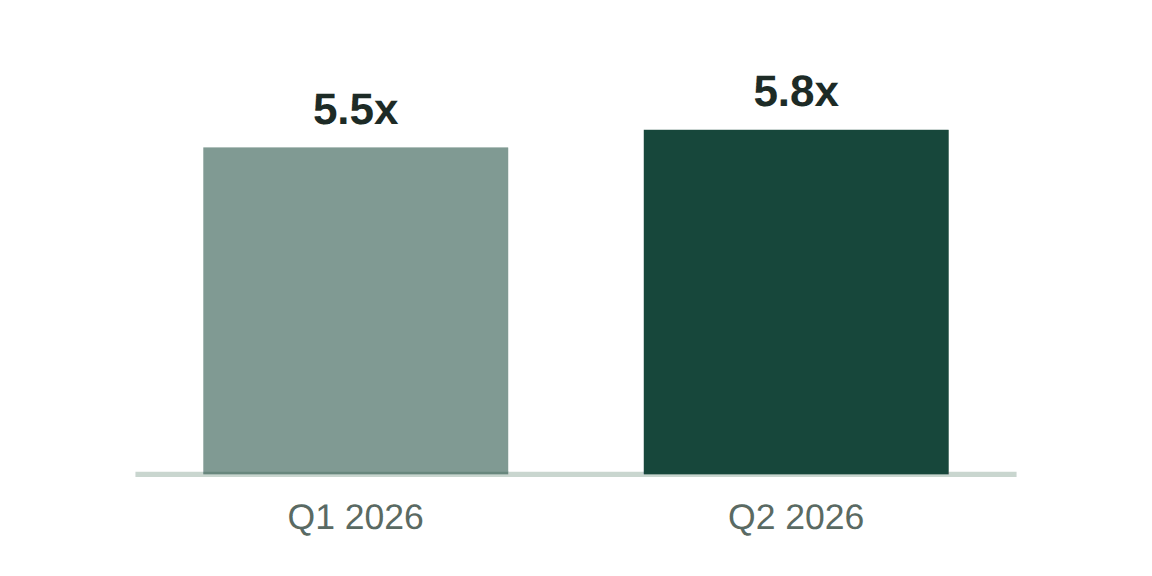
Financing conditions
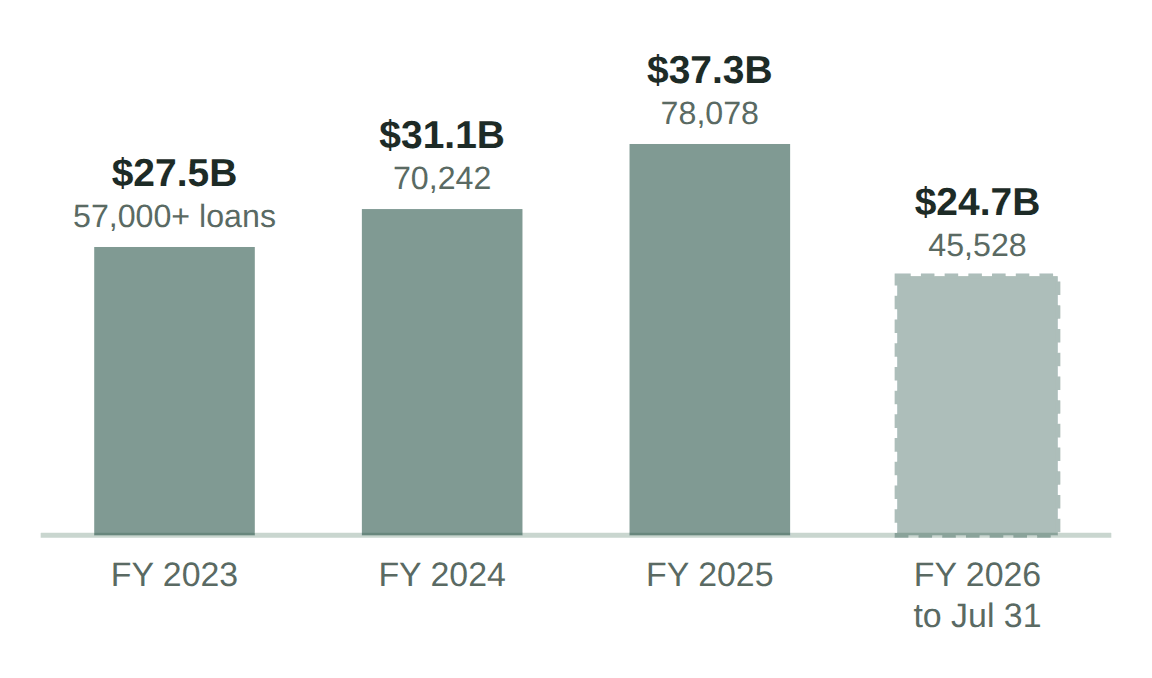
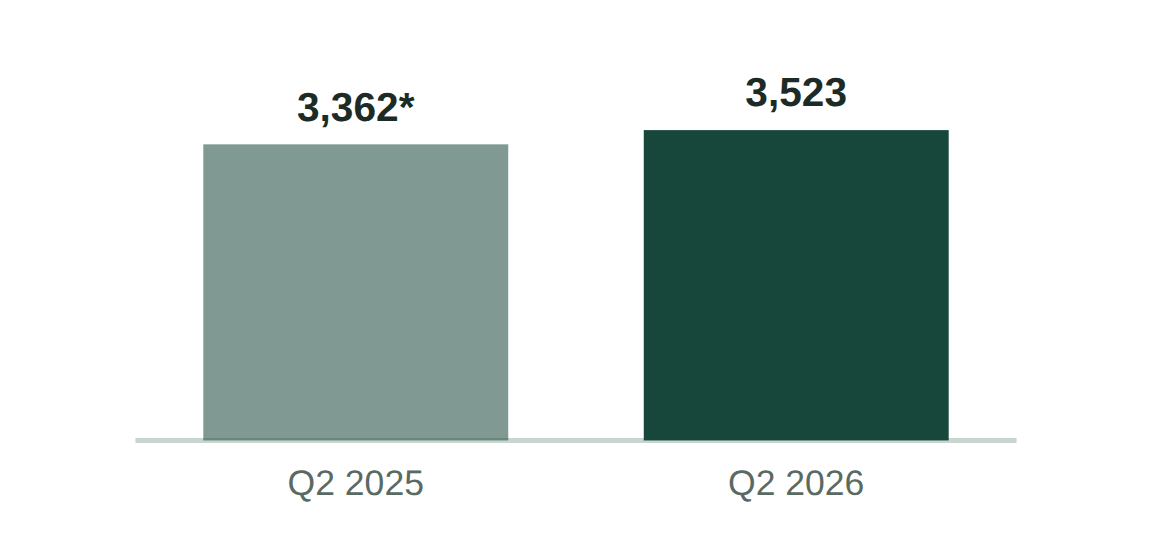
BizBuySell figures are voluntary broker-reported closings. Market Pulse Q2 was completed by 255 intermediaries reporting 181 transactions. FY2026 SBA comparisons run against a record FY2025, and approvals were frozen during the fall 2025 shutdown.
Closed Deals
Six transactions announced this month by Main Street and lower middle market advisors. Terms were not disclosed in any of them, which is the norm at this size. Each tombstone ends with why the deal deserves a broker's attention.
Six-studio martial arts operator (dba Satori Academy), Edison, New Jersey, founded 2007. Buyer is a private-equity-backed youth sports platform founded in 2024.
Why it matters. A multi-unit Main Street service business sold to a sponsor-backed platform rather than an individual. Roll-up capital is now reaching categories that used to trade only to owner-operators.
Justice and government facility architecture, St. Louis Park, Minnesota, founded 1977; 90-plus justice projects across the region. Providus is a Detroit sponsor focused on architecture, engineering and construction services.
Why it matters. A founder-era firm with a defensible niche is exactly what AEC platforms are shopping for. Specialty beats size.
Manufacturer and distributor of specialty threaded fasteners, Dallas, founded 1973; serves infrastructure, power generation, construction and telecom. Rox is an Austin private investment firm founded 2017.
Why it matters. Fifty-year operating history, in-house manufacturing, mission-critical end markets. Industrial distribution with a make-to-spec capability keeps clearing at sponsor multiples.
Multidisciplinary engineering and surveying firm. SAM is a national geospatial and infrastructure services provider and a repeat acquirer.
Why it matters. Surveying and geospatial work is consolidating fast under infrastructure spending. Regional engineering firms with licensed staff are in demand from strategics as well as sponsors.
Asset-management consulting and software for capital-intensive industries, Philadelphia. Buyer provides training and compliance software to nuclear, utility, aerospace and government customers.
Why it matters. A strategic buyer adding an adjacent capability in a regulated vertical. Services-plus-software businesses in safety-critical industries carry a premium.
Property restoration services. Strategic combination within the restoration and disaster-recovery trade.
Why it matters. Restoration remains one of the most active home-services roll-up categories. Recurring insurer relationships and 24-hour response capacity are the assets being bought.
Regulation and Policy
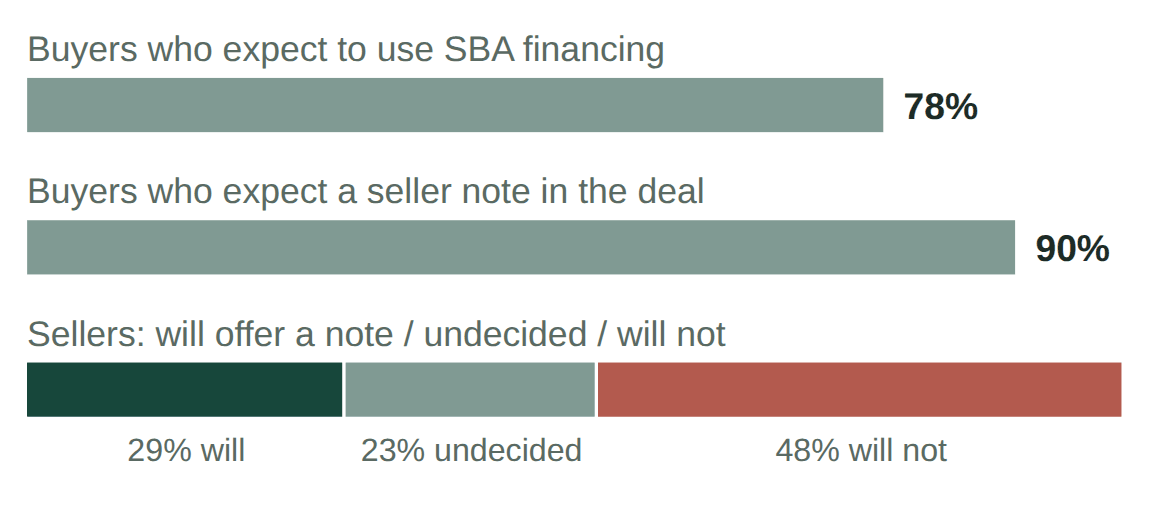
Ordered by the date each item bites. Most of this section concerns SBA acquisition lending, which 78% of surveyed buyers expect to use.
Last day to lock in the current SOP
SOP 50 10 8.1 applies to applications issued an SBA loan number on or after October 1, 2026. Anything with a loan number by September 30 stays under SOP 50 10 8, including its 1.15x coverage test and the ability to lean on projections. If a deal is close, this is the week to push the lender for the number. The FY2026 fee schedule, including the 0% upfront fee on manufacturer 7(a) loans up to $950,000, also applies only to loans approved through September 30.
SOP 50 10 8.1 rewrites change-of-ownership underwriting
Published August 14 under SBA Policy Notice 5000-880695, the new SOP sorts acquisitions into four buckets (initial acquisition, business expansion, owner buyout, and ESOP or cooperative) and sets coverage, equity and diligence rules by bucket. The changes that will move prices:
- Coverage rises to 1.25x from 1.15x for most change-of-ownership loans, and it must be met on historical cash flow. A growth plan no longer papers over a shortfall.
- Quality of earnings becomes mandatory for initial acquisitions and business expansions priced at $3 million or more, on top of the business valuation. Expect a cash proof tying bank activity to tax returns and a customer-concentration review.
- Every acquisition is underwritten as a standard 7(a) loan regardless of size: full credit memo, independent valuation, site visits at both the applicant and the target. Sub-$350,000 deals lose the small-loan shortcut.
- Citizenship tightens. Every direct and indirect owner and required guarantor must be a U.S. citizen or national residing in the United States; entity owners must be organized here. Lawful permanent residents are out, extending the March 1 policy notice into the SOP itself.
- Equity gets real. A 10% minimum injection now reaches business expansions and partner buyouts. Seller standby notes and other non-cash equity, counted together, can cover no more than half of the injection, and lenders must assess post-closing liquidity.
Two items loosen: a longer seller transition period is permitted, and expansion deals by existing operators get more favorable terms. Lenders and counsel are already advising buyers to settle the financing structure before signing a letter of intent.
First Fed hike since 2023; prime at 7.00%
The FOMC voted 12–0 to raise the funds rate to 3.75%–4.00%, citing inflation that remains elevated on energy costs tied to the U.S.–Iran conflict and lingering tariff effects. August CPI ran 3.4% year over year. For 7(a) borrowers the arithmetic is simple: the maximum variable spread on acquisition loans above $350,000 is 3.00% over prime, so the ceiling is now 10.00%; smaller loans can price up to 13.50%. A quarter point adds roughly 1% to the annual payment on a ten-year 7(a) loan, small on its own, but it lands in the same fortnight that coverage moves to 1.25x. The next decision comes October 28, and the September projections leave the door open to another increase before year-end.
FY2027 SBA fee schedule
For loans approved October 1, 2026 through September 30, 2027, qualifying manufacturers (NAICS 31–33) keep a 0% upfront guaranty fee on 7(a) loans, but the cap drops to $700,000 from $950,000. On the 504 side, both the upfront and annual service fees are waived for manufacturers, food supply chain businesses, rural borrowers and 504 debt-refinance loans; other 504 borrowers pay 0.50% upfront and 0.203% annually. Manufacturing listings between $700,000 and $950,000 of debt are the ones that lose an incentive on October 1.
No shutdown on October 1; the next cliff is December 11
A continuing resolution signed in early September funds the government through December 11, so SBA loan processing continues into the new fiscal year. That is a change from a year ago: the 43-day shutdown that began October 1, 2025 froze roughly $170 million of SBA lending a day, and a second lapse hit in early 2026. Full-year FY2027 appropriations still have to be negotiated in a post-election lame-duck session. If a closing depends on an SBA loan number in the second week of December, build in a cushion.
Industry Landscape
Sponsor money is moving down the size ladder
Three of this month's tombstones involve buyers formed in the last four years buying founder-owned firms that a decade ago would have sold to an individual or a local competitor: a 2024-vintage youth sports platform buying a six-studio martial arts school, a 2022-vintage AEC sponsor buying a justice architecture practice, a 2017-vintage firm buying a fastener maker. Supply is cooperating. Axial reports 3,523 deals brought to market in Q2, a record for the platform and up 4.8% year over year, while U.S. private equity entered 2026 with roughly $1.1 trillion of uninvested capital. For brokers with $1M-plus SDE listings, the buyer list should now include add-on platforms alongside individuals and strategics.
The buyer pool is younger and more organized
BizBuySell's Q2 survey found 46% of buyers describe themselves as corporate refugees seeking control of their careers, 14% as serial entrepreneurs and 13% as recently unemployed professionals. Nearly half of brokers report more entrepreneurship-through-acquisition and search-fund activity, with business schools in Texas and elsewhere feeding the pipeline. These buyers arrive with proof of funds, SBA prequalification and advisors, and they compete hard for the same clean, cash-flowing businesses. Profitability now outranks growth potential as the top screening criterion; 86% say they want a recession-resistant business.
The SBA channel is narrower than it was
Through the first nine months of FY2026 the SBA approved 40,824 7(a) loans for $21.8 billion, against 61,270 loans and $27.6 billion in the same window of a record FY2025. Approvals reached $24.7 billion by July 31. The fall shutdown, the March citizenship rule, the 10% equity requirement and full-standby seller notes all took a bite, and October 1 adds another layer. With roughly four in five buyers expecting SBA financing, a listing's SBA eligibility has become a marketability question, not just a financing one. Several brokers surveyed by BizBuySell now recommend a lender pre-review before a business goes to market.
The seller-financing gap has not closed
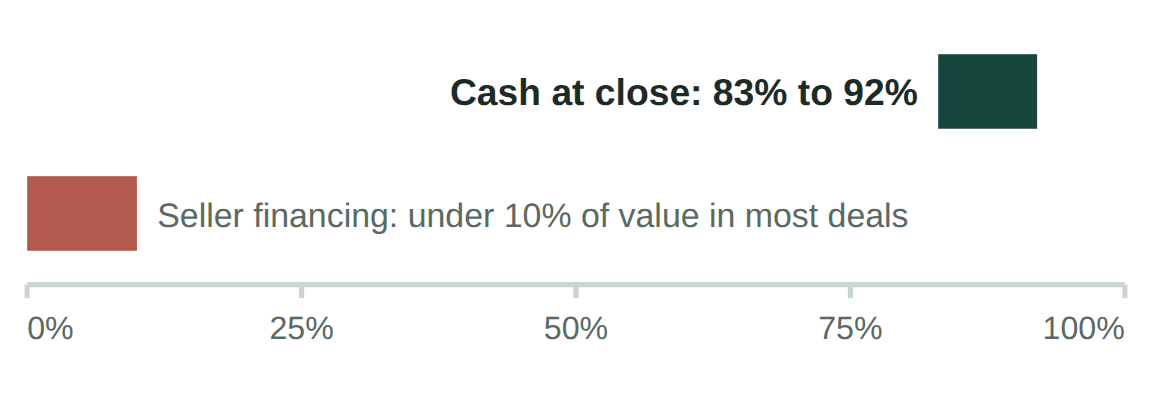
Ninety percent of buyers expect a seller note to be part of the structure; 29% of owners plan to offer one, almost half say they won't, and 23% are undecided. Market Pulse data show seller financing below 10% of deal value in most Q2 closings, under its long-run trend. Under the new SOP a standby note still counts toward the buyer's injection, but only up to half of it, so the note's job shifts from replacing buyer cash to bridging price expectations.
Advisory firms keep scaling
Benchmark International says it held the top spot among privately owned sell-side advisors in PitchBook's Q2 2026 league tables; Generational Group passed 1,900 closed transactions across 17 offices. IBBA now counts more than 3,000 members and has scheduled its Q3 Market Pulse survey for October 1–15. Owners at the upper end of Main Street increasingly choose between a franchise brokerage, a national advisory firm and a boutique, and the national firms are winning on process and buyer databases.
Trends to Watch
Value over volume, and a market split in two
Transactions fell 10% in Q2 while the average multiple rose. Brokers describe a seller's market for businesses with $200,000-plus in SDE and SBA prequalification, and a buyer's market for everything marginal. Roughly three quarters of Market Pulse respondents say the $2M–$50M segment favors sellers; the smallest Main Street deals still favor buyers and often draw only one or two offers.
Deals take longer
Lower middle market timelines stretched to 11–12 months from engagement to close, with the $2M–$5M band jumping from 9 to 11.5 months. Manufacturing sales on BizBuySell took a median 247 days, up 17%, while service businesses improved to 155 days. Longer diligence, tighter underwriting and mandatory QoE will not shorten this.
Sector heat map
Home services and anything with recurring revenue continue to attract multiple bidders. Retail volume fell 15% as high rents and long leases scare buyers, though prices held at a $250,000 median. Restaurants sold at a $205,000 median, down 12%. Manufacturing is the puzzle: median cash flow of sold businesses rose 17%, yet the median price fell 10% to $704,500 and the multiple slipped 7%, a sign buyers are pricing conservatively for tariff and energy exposure.
Margins under energy pressure
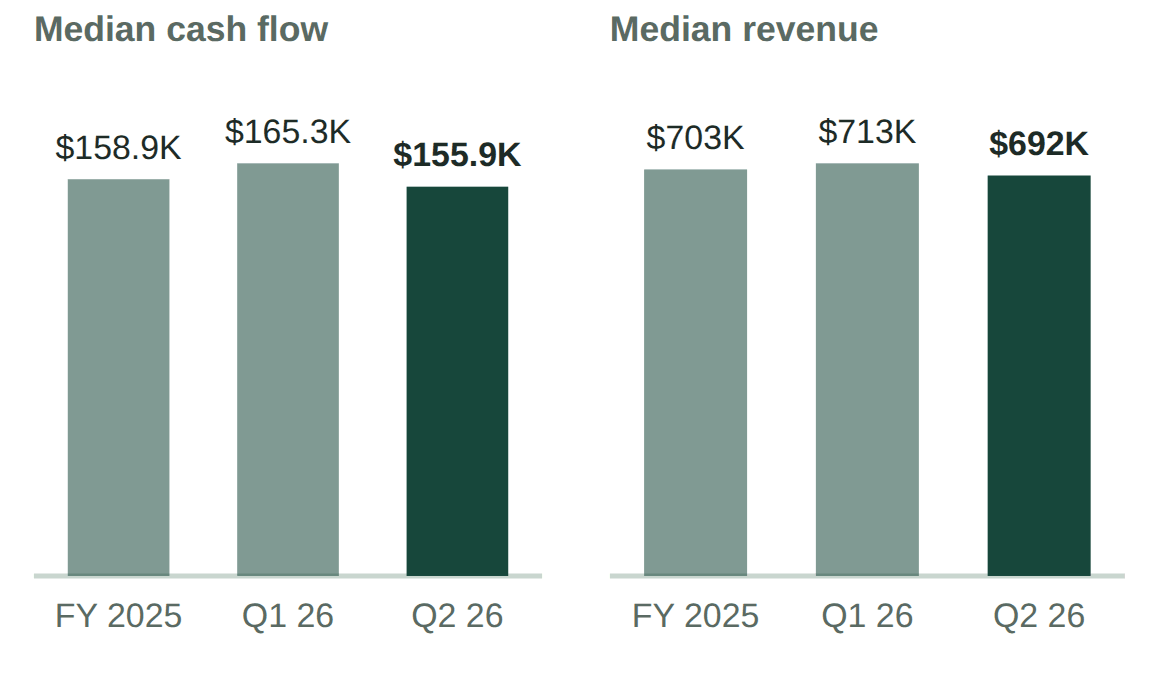
Sixty-three percent of owners say inflation is not easing, and 48% report disruptions from fuel and energy costs following the U.S.–Iran conflict, with transportation and travel-related businesses hit hardest. Median cash flow and revenue of sold businesses each slipped 3%. Expect more add-back scrutiny on fuel, freight and utilities in trailing-twelve-month recasts.
The retirement wave is still a trickle
Retirement is the top reason to sell in every size band, reaching 72% of sales in the $1M–$2M range, yet 60% to 90% of sellers came to market with less than a year of exit planning. Only 14% of owners have a professional valuation and 35% admit they have no idea what their business is worth. Some are winding down or passing the business to family instead of selling. As Calder Capital's Max Friar put it in BizBuySell's report, "the silver tsunami remains a trickle." Brokers who help owners prepare 12 to 24 months out are building the only inventory that will clear the new underwriting bar.
Outlook
Sixty-five percent of brokers expect second-half volume to exceed the same period of 2025, and Market Pulse respondents anticipate more businesses coming to market without broad price increases. The constraint is financeable inventory, not demand.
The Broker's Move This Week
Re-underwrite every SBA-dependent listing at 1.25x coverage on trailing-twelve-month cash flow, priced at prime 7.00% plus the lender's spread. Anything that only worked at 1.15x, or only with projections, needs one of three things before October 1: a price reset, a larger standby seller note structured within the half-of-injection cap, or a buyer who does not need the SBA. For deals already in underwriting, the one question worth asking every lender today is whether the loan number will be issued by Tuesday.
Dates Ahead
Sources
All items are paraphrased from publicly available reports and releases. Deal terms come from advisor announcements and were not independently verified.
- BizBuySell, Q2 2026 Insight Report
- IBBA and M&A Source, Market Pulse Survey Q2 2026 (PR Newswire, Aug. 25, 2026); Q3 survey dates
- SBA, Policy Notice 5000-880695, issuance of SOP 50 10 8.1
- PilieroMazza, Five SBA 7(a) Changes that Could Reshape Business Acquisitions (Aug. 24, 2026); Speritas Capital, SOP 50 10 8.1 analysis (Aug. 27, 2026); Cantrell Law Firm, seller's guide to the new rules
- Federal Reserve, FOMC statement, Sept. 16, 2026; CNBC, Fed rate decision coverage; PrimeRates, inflation and meeting calendar
- Distilled Funding, FY2027 manufacturing fee schedule; Growth Corp, FY2027 504 fees
- Committee for a Responsible Federal Budget, Appropriations Watch FY2027; Federal News Network, 2025 shutdown impact on SBA loans
- Lumos Data, SBA 7(a) FY2026 program performance; SBA Pulse state data via FY2026 YTD approvals; CT Acquisitions, FY2025 totals
- Axial Q2 2026 platform data via Salt Creek Advisory, Lower Middle Market M&A Outlook 2026
- Generational Group, Klein McCarthy Architects and Interstate Threaded Products announcements (Business Wire)
- Benchmark International, press releases, including Edison Martial Arts, SJB Group, P&Ro Solutions Group and Gilco Restoration
- Chart series: BizBuySell Q1 2026 and Q4 2025 Insight Reports, 2025 Year in Review and quarterly media releases (Q2 and Q3 2025 counts); Crestmont Capital, SBA 7(a) loan statistics (FY2023 and FY2024 totals); Federal Reserve FOMC decisions for the prime-rate steps
Main & Market is published every quarter for business brokers, M&A advisors, lenders and the owners and buyers they serve. It summarizes publicly available information and is not legal, tax, lending or investment advice. Confirm SBA program terms with a participating lender and current SOP text before relying on them.
Main & Market, 120 Birmingham Dr, Ste 110B, Cardiff, CA 92007 · kenny@sdbiz.com